PRESS RELEASE: Weekly Update – Global Fertiliser Markets – w/e 23.10.2026: INDIA PREPARES TO RETURN TO UREA MARKET AS GLOBAL FERTILISER SUPPLY PRESSURES INTENSIFY
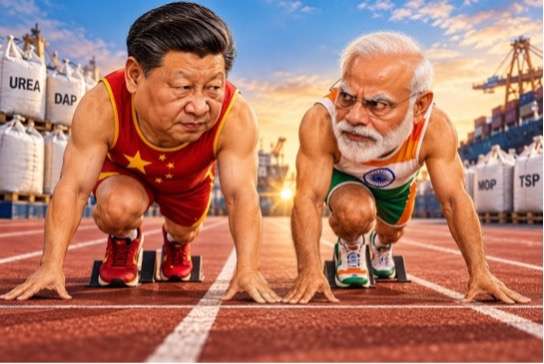
• UREA: India is expected to return to the market with another major tender, with Chinese producers positioned to secure substantial volumes as global supply remains constrained.
• PROCESSED PHOSPHATES: Weak demand and high prices continue to encourage buyers to consider alternative phosphate products, including Triple Superphosphate (TSP).
• POTASH: Prices diverge across major markets, with Brazilian values softening while Southeast Asian prices remain comparatively firm.
• AMMONIA: European gas costs, Middle Eastern supply disruptions and reduced Asian export availability continue to support higher ammonia prices.
UREA – Stable to Firm
China – Prilled Urea: Indicative USD 345–350 PMT FOB netback
China – Granular Urea: USD 440 PMT FOB
North Africa – Egypt: USD 535 PMT FOB
Brazil – Non-Chinese Urea: Approximately USD 490 PMT CFR
Middle East: USD 430–440 PMT FOB
US/NOLA – January Barge: Above USD 480 PMT CFR
Global urea markets were comparatively quiet during the week, although stronger North African prices and expectations of another major Indian tender supported market sentiment.
India is expected to return to the market with a tender potentially approaching 2 million metric tonnes (MT), following the disappointing outcome of its previous tender, which secured only 410,000 MT against a target of 1.7 million MT.
Chinese producers rejected the low returns offered under the previous tender, but expectations of a new Level 1 (L1) benchmark around USD 375 PMT CFR could provide netbacks of approximately USD 345–350 PMT FOB, potentially attracting substantial Chinese participation.
China continues to hold significant urea inventories, with domestic demand subdued and export markets offering considerably stronger returns.
Elsewhere, Egyptian producers secured sales at approximately USD 535 PMT FOB, with Europe considered a likely destination. Brazilian demand remains constrained by agricultural credit restrictions and seasonal conditions, while US/NOLA activity remains subdued outside the main purchasing season.
Middle Eastern producers continue to face disruptions associated with the Strait of Hormuz, although limited cargoes are reaching customers in Brazil and Thailand.
Further pressure on global nitrogen supply emerged with Nutrien’s announcement of an indefinite shutdown of its Trinidad nitrogen operations, reflecting ongoing natural gas supply constraints. The closure reinforces the vulnerability of fertiliser production to energy availability and cost.
Outlook: India’s anticipated tender is expected to provide the next major price signal. Chinese participation could restore momentum to prilled urea markets, while supply constraints and European purchasing requirements support broader price stability.
PROCESSED PHOSPHATES – Stable to Soft
Brazil – MAP: Up to USD 850 PMT CFR
India – DAP: USD 890–900 PMT CFR
Global processed phosphate markets remain characterised by subdued demand and constrained supply, with buyers increasingly resistant to prevailing prices.
Brazilian Monoammonium Phosphate (MAP) prices have continued to decline over recent months, while Indian Diammonium Phosphate (DAP) prices remain relatively stable despite limited purchasing activity.
Supply constraints remain significant.
Disruptions affecting sulphur shipments through the Strait of Hormuz continue to increase production costs, while China’s restricted phosphate exports have reduced international availability.
High raw material costs are also placing pressure on producer margins, with some manufacturers reducing output rather than accepting lower finished-product prices.
An emerging development is growing interest in Triple Superphosphate (TSP) as an alternative to MAP and DAP.
TSP does not require ammonia and generally requires less sulphur in production, potentially providing a more economical phosphate source for price-sensitive agricultural markets.
Morocco’s OCP has increased its focus on TSP production, reflecting changing purchasing preferences among major importers.
Outlook: Processed phosphate prices are expected to remain under pressure as weak demand offsets restricted supply. Increasing substitution towards TSP may further influence the market for traditional phosphate products.
POTASH – Stable to Soft
Brazil – Granular MOP: USD 355–375 PMT CFR
Southeast Asia – Standard MOP: USD 370–420 PMT CFR
Southeast Asia – Granular MOP: USD 425–435 PMT CFR
Global potash markets continue to show contrasting regional trends, with prices softening in Brazil while Southeast Asian markets demonstrate greater resilience.
Brazilian demand is easing as the principal soybean planting period concludes, with granular Muriate of Potash (MOP) prices remaining between USD 355–375 PMT CFR.
In Southeast Asia, stronger seasonal agricultural demand is supporting prices, with standard MOP reaching approximately USD 416 PMT CFR following an Indonesian purchasing tender.
International supply developments are also influencing the longer-term outlook.
The resumption of Belarusian potash shipments to the United States following sanctions relief represents a potential change in established trade flows, although transportation costs may limit their immediate influence on North American prices.
Meanwhile, Canada’s Canpotex is pursuing additional export infrastructure capacity, reflecting expectations of sustained international demand.
The US Government has also announced a USD 1.34 billion domestic fertiliser manufacturing investment programme, including projects intended to expand American potash production and reduce import dependence.
Outlook: Potash prices are expected to remain relatively stable in the near term, although weaker Brazilian demand and additional global production capacity may create downward pressure.
AMMONIA – Firming
Europe – Duty-Paid Ammonia: USD 710–720 PMT CFR
Middle East: USD 450–490 PMT FOB
East Asia: USD 490–530 PMT CFR
Global ammonia prices continued to strengthen during the week, supported by higher European natural gas costs, production disruptions and restricted export availability from several major producing regions.
West of Suez, elevated European gas prices are increasing ammonia manufacturing costs and encouraging production curtailments, supporting demand for imported product.
The indefinite closure of Nutrien’s Trinidad nitrogen complex adds further uncertainty to Atlantic Basin supply, highlighting the continuing importance of reliable natural gas availability.
East of Suez, limited exports from China and Indonesia, combined with stronger demand from South Korea and Taiwan, are supporting expectations that regional prices have established a floor.
A notable development was the reported sale of a 30,000 MT Chinese ammonia cargo to Morocco’s OCP, demonstrating how changing supply conditions are encouraging new international trading relationships.
Disruptions affecting the Strait of Hormuz continue to influence established ammonia shipping routes and regional supply availability.
Outlook: Ammonia prices are expected to remain firm, with European energy costs and constrained Asian supply providing continuing support.
GLOBAL FERTILISER SUPPLY SECURITY RETURNS TO THE FOREFRONT
Australian Fertiliser Corporation CEO Stein Haugan said recent developments demonstrate the increasing importance governments are placing on secure domestic fertiliser production.
“The US Government has announced support for eight domestic fertiliser manufacturing projects representing a combined investment of USD 1.34 billion, including initiatives intended to expand American potash production and reduce import dependence, recognition that fertiliser supply is fundamental to national agricultural and economic security.”
“At the same time, developments in Trinidad and continuing disruptions in the Middle East demonstrate how quickly international fertiliser availability can be affected by energy constraints and geopolitical events.”
“For Australia, these developments continue to reinforce the importance of building greater domestic fertiliser production capacity and reducing exposure to international supply disruptions.”
ENDS